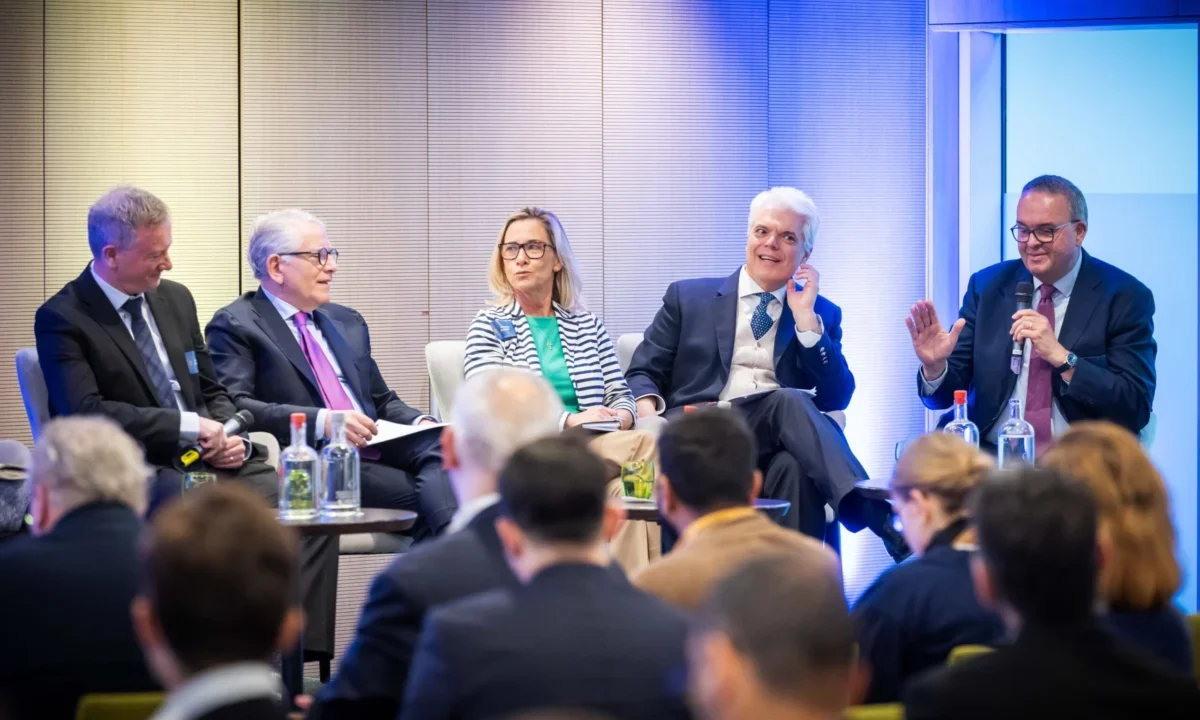

As the global economy grapples with the dual pressures of rapid technological transformation and intensifying geopolitical fragmentation, the world’s leading fiscal policy experts gathered recently to address the critical intersection of tax law, innovation, and state sovereignty. The recent summit served as a high-level forum to deconstruct how governments can remain competitive while managing the budgetary pressures of an AI-driven labor market and a shifting European regulatory framework.
The conference, which featured a diverse assembly of economists, policy analysts, and government advisors, focused on three distinct pillars: the disruptive potential of Artificial Intelligence (AI) on tax revenue models, the localized impact of French domestic politics on European integration, and the broader challenges of maintaining foreign direct investment (FDI) amidst escalating global trade tensions.
I. Main Facts: The Nexus of Disruption
The central thesis of the summit was clear: the traditional tax base, which has historically relied on labor income, is facing an existential crisis. With the integration of generative AI and automation across professional services, manufacturing, and creative industries, the link between human productivity and taxable income is becoming increasingly tenuous.
Key takeaways from the opening keynote included:
- The Labor-Revenue Gap: As AI increases productivity while potentially displacing human workers, governments face a "revenue crunch." If the tax system continues to favor labor over capital, the shift toward automated workforces could lead to a permanent depletion of social security and income tax funds.
- Innovation as a Tax Catalyst: Policymakers are urged to rethink the definition of "taxable value." Does value creation lie in the algorithm, the data, or the end-product? The consensus suggests that a radical redesign of corporate taxation is required to capture value generated by intangible assets.
- Global Competition: The race to host AI infrastructure has ignited a new form of tax competition. Nations are now competing not just for capital, but for the energy infrastructure and data centers that underpin the AI economy.
II. Chronology of the Policy Sessions
The event was structured to move from the abstract challenges of technology to the granular realities of European and global tax governance.
The Opening Keynote: AI and the Future of Tax
The summit commenced with an exploration of the "Fourth Industrial Revolution." The keynote speaker argued that the disruption caused by AI is not merely technological but systemic. The session analyzed how tax policy must evolve from taxing "human hours" to taxing "computational output." Discussions highlighted the need for international cooperation to prevent a "race to the bottom" in corporate tax incentives for tech firms.
Session 1: The French Political Calculus
Mid-morning sessions shifted focus to the Gallic perspective. The dialogue explored how the incoming presidential tax agenda will interface with the broader European Union (EU) mandate. With France seeking to position itself as a European hub for innovation, the panel debated the efficacy of tax credits for R&D versus direct subsidies. The critical question posed: How does a nation balance the populism of domestic tax relief with the cold, hard requirements of EU fiscal discipline?
Session 2: The EU Legislative Pipeline
Following the French overview, the focus widened to the EU’s legislative agenda. This session provided a technical deep-dive into the "Omnibus package" and the "DAC (Directive on Administrative Cooperation) recast." Attendees were briefed on the latest progress regarding the OECD’s Pillar One—the initiative to reallocate taxing rights—and the complexities of the Mobility Map, which governs the tax treatment of cross-border workers in a remote-work era.
Session 3: FDI and the Trade War Reality
The final substantive session addressed the geopolitical elephant in the room: trade wars. As tariffs rise and protectionist sentiments grow, the panel examined how Pillar Two (the global minimum tax) interacts with foreign direct investment. The session concluded with a debate on what constitutes "healthy" tax competition in an era where global supply chains are being forcibly reconfigured.
III. Supporting Data and Technical Frameworks
To understand the scale of the challenges discussed, one must look at the technical architecture currently being negotiated in Brussels and Paris.
The MFF and Own Resources
The Multiannual Financial Framework (MFF) remains the bedrock of EU spending. Recent updates suggest a push for "Own Resources"—tax revenues that flow directly to the EU budget rather than through member state contributions. This includes potential levies on plastic waste, emissions trading, and digital services. Data presented at the conference suggests that if these resources are fully implemented, the EU could close a projected €15–20 billion budgetary gap by 2027.
Pillar One and Two Dynamics
- Pillar One: Aimed at taxing digital giants where they sell, rather than where they are headquartered. The challenge remains the lack of ratification in key jurisdictions, including the United States, creating a "two-speed" international tax system.
- Pillar Two: The 15% global minimum tax is now a reality for many MNEs (Multinational Enterprises). However, the session highlighted "compliance fatigue," as businesses struggle to navigate the divergent local implementations of the global rulebook.
IV. Official Responses and Expert Consensus
During the sessions, representatives from various fiscal policy think tanks offered a synthesis of the current climate. Dr. Elena Rossi, a lead economist on the EU policy panel, noted, "We are transitioning from an era of tax optimization to an era of tax transparency and compliance. The burden on the taxpayer has shifted from calculating liabilities to managing regulatory complexity."
When asked about the French tax agenda, the consensus was that while the French government remains committed to pro-business tax cuts to boost competitiveness, it is constrained by the Stability and Growth Pact. The official response from the policy desks suggests that France will continue to push for "EU-wide digital tax floors" to prevent internal erosion of the tax base, effectively "exporting" their domestic tax philosophy to the rest of the bloc.
V. Implications: The Path Forward
The implications of the summit are profound for both the private sector and sovereign states.
For the Private Sector: The Cost of Complexity
Multinational corporations must prepare for a future where tax compliance is no longer a back-office function but a strategic risk. The interaction between Pillar Two and domestic tariff policies means that businesses can no longer assume that a lower headline tax rate will equate to a higher net profit. The "tax-efficient" structure of the 2010s is effectively obsolete.
For Sovereign States: Reclaiming Fiscal Sovereignty
The sessions underscored that states are fighting to reclaim fiscal autonomy in a digital world. By focusing on "Own Resources" and the DAC recast, the EU is attempting to create a more resilient, integrated fiscal block. However, this comes at the cost of sovereignty; member states are increasingly finding their tax policy space narrowed by European-level mandates.
The Societal Shift
Perhaps the most significant implication discussed was the social contract. If AI replaces the tax-paying human worker, the revenue to fund healthcare, infrastructure, and education must come from elsewhere. The proposal of an "AI tax" or a "Robot levy," while controversial, moved from the fringes of debate to the center of the policy room. It is no longer a question of if these mechanisms will be considered, but how they can be implemented without stifling the very innovation they aim to tax.
Conclusion
The fiscal landscape is undergoing a tectonic shift. As we navigate the complexities of trade wars, the integration of AI, and the reform of the European tax architecture, one thing remains clear: the old models are insufficient for the new reality. The summit concluded on a note of cautious optimism—a recognition that while the challenges are unprecedented, the mechanisms for international cooperation, through the OECD and EU frameworks, are more robust than ever before. The future of tax will not be found in the archives of the 20th century, but in the agile, data-driven, and internationally coordinated policies currently being drafted in the halls of power.
