
In a landmark ruling that reinforces the principle of contractual finality in insurance law, the U.S. 11th Circuit Court of Appeals has ruled against Zurich American Insurance Co., effectively barring the carrier from reclassifying property losses after payments have already been issued. The decision, handed down on October 22, serves as a stern reminder to the insurance industry regarding the legal consequences of "coverage pivots" and the waiver of rights through voluntary performance.
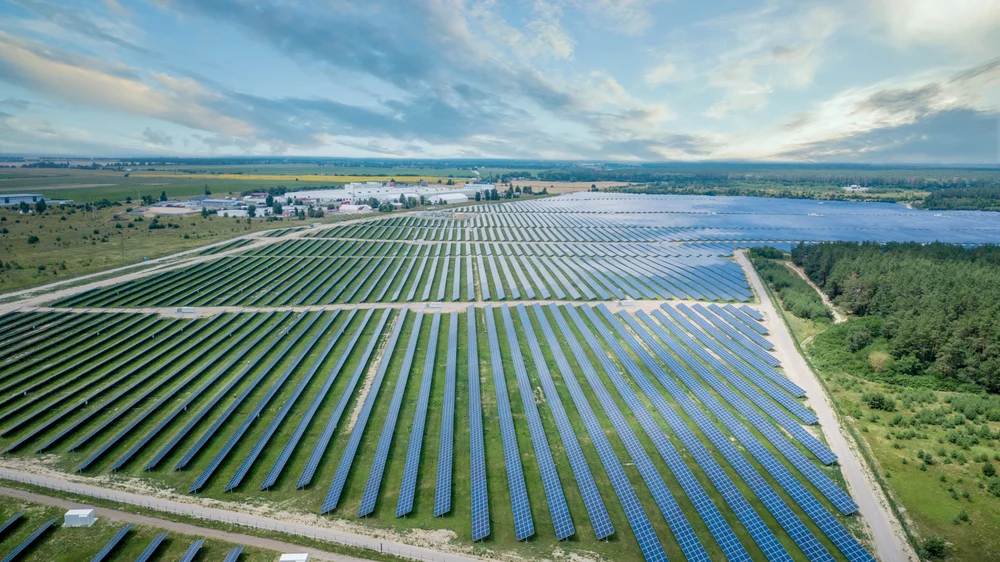
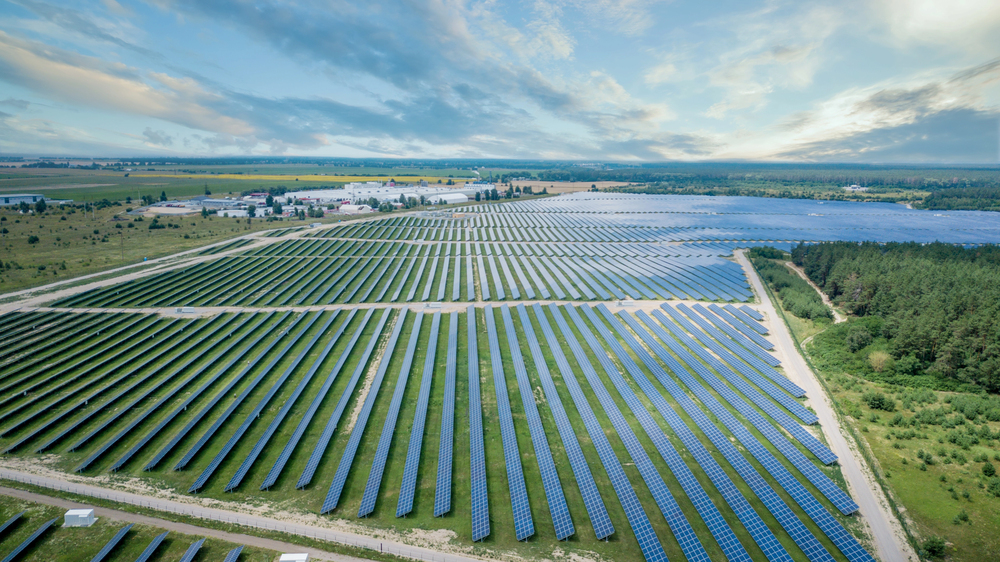
The dispute stems from a multi-million dollar construction insurance claim involving First Solar and a 200-megawatt solar farm project located near Warner Robins, Georgia. At the heart of the litigation was a fundamental disagreement over whether heavy rainfall that caused significant equipment damage should be categorized as standard "water damage" or as a "flood event"—a distinction that carried a swing of millions of dollars in deductible obligations.
Writing for the panel, U.S. Circuit Judge Embry Kidd delivered a colorful yet legally stinging rebuke of Zurich’s attempt to retroactively change its position: "Golfers get mulligans. But in this case, the insurance company does not."
A Chronology of the Dispute
The controversy began in 2018 when First Solar initiated the development of a massive solar energy installation in central Georgia. As part of its risk management strategy, the firm secured a builder’s risk policy from Zurich American. This policy was designed to cover unforeseen physical damage during the construction phase, including standard environmental hazards.
Between 2019 and 2020, the project site was battered by five distinct heavy rain events. These weather patterns resulted in significant standing water across the site, causing extensive degradation to solar components and electrical infrastructure.
The Initial Assessment
Following the first three rainfall events, Zurich’s designated adjuster conducted an on-site evaluation. The conclusion was straightforward: the damage was classified as "water damage." Under the specific language of the policy, water damage carried a relatively modest $100,000 per-event deductible. Acting on this determination, Zurich moved forward with the claims process, issuing advance payments to First Solar totaling $600,000.
The Reversal
Months later, Zurich abruptly reversed its stance. Citing a re-evaluation of the site’s hydrology and meteorological data, the insurer argued that the 2019 and 2020 deluges were, in fact, "flood events." Under the terms of the policy, flood-related damage was subject to a significantly higher deductible: $2.5 million per event.
By applying this higher threshold, Zurich contended that the total damage incurred across the events failed to exceed the deductible, thereby rendering the company immune from further liability. Consequently, Zurich sought to recoup its previous payments or offset them against future claims, triggering a fierce legal battle.
The Litigation Landscape
First Solar initiated litigation in the U.S. District Court for the Middle District of Georgia, challenging the insurer’s right to retroactively recharacterize the claims. The firm argued that Zurich’s original classification was accurate, and even if it were not, the company had already accepted the liability and paid the claims, thereby waiving its right to assert a different, more restrictive interpretation of the policy.
The District Court Verdict
The case proceeded to a jury trial, where the evidence presented centered on the technical definition of "water damage" versus "flood." The policy defined water damage as "all damage caused by water, whatever the source, whether or not driven by wind, other than that otherwise defined as flood or that resulting from a named storm."
First Solar’s team bolstered their argument by noting that the site was located in a Level 3 flood zone—an area categorized as having only a moderate risk of flooding. They also highlighted the intervention of their insurance agent, John Shaw, who had explicitly urged Zurich to categorize the events as water damage based on the policy definitions. The jury ultimately found in favor of First Solar, and the district judge entered a judgment for $12.2 million, which included significant prejudgment interest.
Appellate Review: The Doctrine of Waiver
Both parties appealed aspects of the district court’s ruling. The 11th Circuit’s review focused on a critical intersection of contract law and insurance practice: the doctrine of waiver.
While the appellate panel conceded that, strictly speaking, the policy language might have technically allowed for a "flood" classification for some of the events, the court ruled that Zurich had effectively forfeited its right to rely on that classification. By paying the initial claims without reserving its rights—a standard legal procedure where an insurer notifies the policyholder that it is investigating a claim but reserves the right to deny coverage later—Zurich signaled its acceptance of the "water damage" classification.
"The central question in this appeal is whether Georgia law permits an insurer in Zurich’s situation to take a mulligan—to receive a do-over after messing up the first time," Judge Kidd wrote. "Or, under Georgia law, did Zurich’s conduct waive its right to apply the flood deductible after previously applying the water damage deductible?"
The court’s answer was an unequivocal "yes." By paying the claims without an explicit reservation of rights, Zurich had, in the eyes of the court, "hooked its tee shot into the woods." The court upheld the lower court’s decision regarding the first three rain events, while remanding the case for further deliberation on the final two events, where the timeline of payments and notices differed.
Interpreting Policy Limitations
Beyond the issue of reclassification, the 11th Circuit addressed a technical but vital procedural point: the policy’s "suit-limitation" provision. Zurich had argued that the lawsuit was time-barred, claiming that the policy required legal action to commence within 12 months of the event.
The court rejected this interpretation, finding the policy’s language ambiguous and insufficient to act as a strict statute of limitations. "Accordingly, we conclude that the suit against the company provision is not a suit-limitation provision," the judges ruled. This aspect of the decision provides a significant win for policyholders, as it limits the ability of insurers to use obscure or poorly drafted clauses to evade liability by claiming that a policyholder waited too long to file suit.
Broader Implications for the Insurance Industry
This ruling serves as a cautionary tale for insurance carriers and their adjusters. The "mulligan" denied to Zurich highlights several critical takeaways for the industry:
- The Necessity of Reservation of Rights: Insurers must be hyper-vigilant about issuing formal "Reservation of Rights" letters at the outset of any claim investigation. Failing to do so before issuing payments can effectively lock the insurer into a coverage interpretation that may be difficult to reverse later.
- The Risks of "Pivot" Strategies: Courts are increasingly skeptical of insurers who, upon realizing the extent of their financial exposure, attempt to re-examine policy definitions to trigger higher deductibles or exclusionary clauses. Once an insurer has made a formal coverage determination, it carries a heavy burden to prove that such a determination was based on a fundamental error that can be rectified without prejudicing the insured.
- Ambiguity Favors the Insured: As seen in the court’s interpretation of the suit-limitation provision, the legal principle of contra proferentem remains alive and well. Ambiguities in policy drafting—whether in coverage definitions or procedural limitations—will almost always be interpreted against the drafter (the insurer) and in favor of the policyholder.
- Documentation is Paramount: The involvement of First Solar’s insurance agent in advocating for a specific classification underscores the importance of clear communication between brokers, policyholders, and carriers during the adjustment process. Contemporaneous documentation of these discussions played a role in the court’s perception of the case.
As the case returns to the district court for further deliberations on the final two rain events, the insurance industry is left with a clear directive from the appellate level. When it comes to claims adjustment, diligence is not merely an operational best practice; it is a legal requirement. Once a path is chosen, the opportunity for a "do-over" is, in the eyes of the 11th Circuit, effectively non-existent.
