
By Simon Thomsen
The fiscal year 2026 (FY26) has proven to be a defining stress test for the Australian venture capital landscape. For ASX-listed Bailador Technology Investments (BTI), the year was defined by a delicate balancing act: maintaining the confidence of dividend-seeking shareholders while grappling with the tectonic shifts in software-as-a-service (SaaS) valuations brought on by the rapid, and at times disruptive, rise of generative artificial intelligence.
While the broader "SaaSpocalypse"—a term used to describe the compression of SaaS multiples amid shifting interest rates and technological pivots—has claimed many victims, Bailador has largely weathered the storm. However, as the dust settles on the annual report, it is clear that the shadow of AI is now the primary lens through which the market views every valuation in the technology sector.
The Main Facts: Stability Amidst Volatility
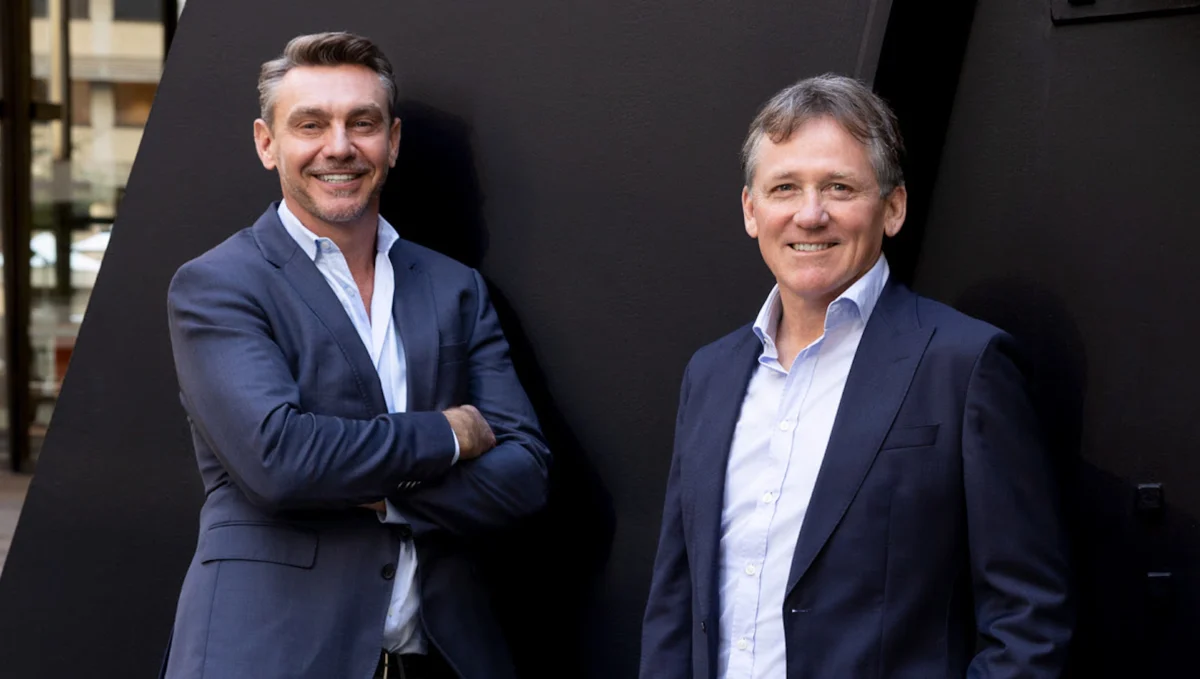
Bailador Technology Investments, led by co-founders Paul Wilson and David Kirk, recently released its FY26 financial results, revealing a landscape of steady operational performance tempered by market-wide valuation recalibrations.
The headline figure for investors is the maintenance of a consistent dividend payout. Despite the headwinds, shareholders will receive a fully franked final dividend of 3.5 cents per share. While this represents a marginal tightening from the 3.6 cents per share distributed in FY25, it signals a commitment to yield that is rare among venture-focused investment vehicles.
However, the core of the portfolio’s valuation remains under pressure. The "jitters" mentioned in the report refer to the market’s uncertainty regarding the longevity of traditional SaaS business models. As AI agents and autonomous software solutions threaten to cannibalize the subscription-based revenue models that have defined the last decade of venture capital, investors are demanding higher growth rates for lower multiples. Bailador’s portfolio companies, while growing their underlying revenue, have seen their "paper" valuations hit by these broader market-sector multiple compressions.
Chronology: The Road to the FY26 Crossroads
To understand where Bailador stands today, one must look at the progression of the last 24 months.
Early FY25: The Initial AI Pivot
As the generative AI boom took hold in late 2024, the initial reaction from the investment community was euphoric. However, as 2025 progressed, the "AI effect" turned bifurcated. Companies that could integrate LLMs (Large Language Models) effectively were rewarded, while those viewed as "legacy SaaS" faced a valuation wall. Bailador spent this period assessing which of their portfolio assets were "AI-defensible" and which were "AI-vulnerable."
Mid-FY25: The Rate Environment Tightens
Persistent inflationary pressures in the Australian economy led to a high-interest-rate environment that discouraged speculative growth. Bailador moved to preserve cash and focus on companies with clear paths to profitability rather than pure top-line expansion.
FY26: The Year of Calibration
By the start of the 2026 fiscal year, the market had largely accepted that the "easy money" era was over. The SaaSpocalypse reached its peak as institutional investors began to re-rate tech stocks based on long-term AI-driven productivity rather than just recurring revenue. Bailador’s board spent the latter half of the year working with portfolio management teams to pivot product roadmaps toward AI integration, ensuring that the core services remained essential rather than redundant.
Supporting Data: Dissecting the Portfolio Health
The resilience of the dividend, despite the valuation headwinds, is rooted in the cash-generating capacity of Bailador’s underlying assets.
Revenue Growth vs. Multiple Compression
While internal valuations for some assets have seen stagnation or minor mark-downs, the underlying revenue growth of the portfolio remains robust. Data indicates that a significant majority of Bailador’s key holdings achieved double-digit top-line growth throughout FY26.
The disconnect between revenue growth and valuation—the "valuation gap"—is primarily a result of market sentiment. If the market assigns a 10x revenue multiple to a company that previously enjoyed a 15x multiple, the company is technically "worth" less on the books, even if the business itself is healthier and more profitable than it was a year ago.

The Dividend Strategy
Bailador’s dividend policy is supported by realized exits and operational cash flows. The ability to pay a 3.5-cent dividend, despite the volatility, underscores the firm’s strategic focus on "expansion-stage" companies—those that have already achieved product-market fit and are generating significant revenue, rather than early-stage startups that burn through capital.
Official Perspectives: The Leadership View
In their commentary accompanying the FY26 results, Paul Wilson and David Kirk emphasized the distinction between "market price" and "intrinsic value."
"We are currently navigating a market that is hyper-focused on the potential for AI to disrupt software," Wilson noted. "The ‘jitters’ the market is experiencing are natural. Investors are trying to differentiate between companies that will be rendered obsolete by AI and those that will be supercharged by it."
David Kirk added: "Our focus at Bailador remains on the fundamentals. We aren’t interested in chasing the hype cycle. We look for companies that provide essential infrastructure for businesses. Whether it’s AI or any other technology, if the product is embedded in the customer’s workflow and delivers a clear ROI, that company will thrive. Our dividends are a reflection of that underlying utility."
The leadership team expressed confidence that the current valuation compression is a temporary market phenomenon. They argue that once the market settles on a "new normal" for SaaS multiples in the age of AI, the valuations of their portfolio companies will naturally recover as their revenue growth continues to outpace the broader economy.
Implications: What This Means for the Future
The FY26 results for Bailador offer a roadmap for how venture capital firms must adapt to the new economic reality.
1. The Death of the "Growth-at-All-Costs" Model
The era of valuing companies based solely on aggressive customer acquisition is over. The "SaaSpocalypse" has mandated a shift toward unit economics. Bailador’s portfolio, by focusing on mature SaaS assets, is well-positioned to survive, but it highlights that future investments will require a rigorous audit of how AI will either complement or compete with the company’s core offering.
2. Dividend Stability as a Competitive Advantage
In an era where many tech-focused funds have had to suspend distributions to shore up their own balance sheets, Bailador’s ability to pay a consistent dividend acts as a massive signal of confidence to the market. It differentiates them from higher-risk, non-listed venture funds that lack transparency or the ability to return capital to investors in lean times.
3. The AI "Show-Me" Phase
The market has entered a "show-me" phase regarding AI. Investors are no longer impressed by companies claiming to use AI; they want to see the bottom-line impact. For Bailador, the challenge in FY27 will be to demonstrate that their portfolio companies have successfully integrated AI to lower churn and increase the value of their existing customer base.
4. A Potential Rebound
If the market’s "jitters" over AI begin to subside and investors return to valuing tech companies based on their actual cash flows and long-term moat, Bailador’s portfolio—which has been conservatively valued during this period of uncertainty—could be primed for a significant upward re-rating.
Conclusion: A Measured Outlook
Bailador Technology Investments stands at a unique junction. By navigating the SaaSpocalypse with a focus on dividend stability and underlying business performance, the firm has provided a safe harbor for investors during a turbulent year.
The "AI jitters" are a temporary, albeit significant, hurdle. As the technology matures, the distinction between hype and utility will become clearer. If Bailador’s portfolio companies can continue to grow their revenues while integrating the productivity gains of AI, the current valuation compression may simply be remembered as a buying opportunity rather than a structural decline.
For now, the message from Wilson and Kirk is clear: the fundamentals are sound, the cash flow is reliable, and the strategy remains fixed on long-term value creation, regardless of the noise coming from the broader market. As we head into FY27, all eyes will be on whether the market sentiment catches up to the reality of the business growth, or if the SaaS sector requires a further fundamental rethink in the face of the AI revolution.
