
In the evolving landscape of global fiscal policy, a provocative new thesis has emerged. Legal scholar Reuven Avi-Yonah, in a forthcoming article for the Tax Law Review titled "Taxation and Deglobalization," posits a bold economic theory: if a nation effectively "fixes" its corporate tax base—specifically through the implementation of full expensing and other structural adjustments—the traditional economic anxieties surrounding high corporate income tax (CIT) rates effectively vanish.
Avi-Yonah’s argument is part of a growing intellectual movement that suggests policymakers can decouple tax rates from economic distortion. However, this line of reasoning has sparked a rigorous debate among economists and tax policy analysts. While many agree that broadening the tax base is a pro-growth imperative, the assertion that such reforms provide the "fiscal cover" to impose a top marginal corporate tax rate as high as 80 percent is being met with significant skepticism.
The Core Argument: Fixing the Base to Raise the Rate
The contemporary tax policy discourse has seen a shift toward the mantra: "Fix the base, raise the rate." Scholars such as Kimberly Clausing, Jason Furman, Michael Linden, and Samantha Jacoby have all explored ways to make the corporate tax code more robust. The objective is to curtail profit shifting—the practice by which multinational corporations move taxable income from high-tax jurisdictions to low-tax havens.
By transitioning to a more efficient tax base, these analysts argue, governments could capture revenue that currently leaks out of the system. Avi-Yonah takes this logic to its logical, albeit radical, extreme. He suggests that if the U.S. were to adopt a system that includes full expensing of capital investments, the "distortive" nature of high corporate rates would be neutralized. In his view, a progressive structure that hits a staggering 80 percent on profits exceeding $10 billion would be not only possible but, in a "deglobalizing" world, potentially feasible.
Chronology of the Debate: From Neutrality to Radical Progressivity
The theoretical foundation of this debate lies in the "Hall-Jorgenson" framework, a standard economic model used to calculate the "user cost of capital." Historically, the tax code has been viewed as a deterrent to investment because it forces businesses to wait years to depreciate capital investments, thereby reducing the net present value of those investments.
- The Pro-Growth Consensus: Over the last decade, economists have reached a near-consensus that "full expensing"—allowing businesses to immediately deduct the full cost of new equipment or technology—is one of the most effective ways to boost worker productivity and economic growth.
- The Academic Shift: Recent years have seen a pivot toward the idea that if the base is "perfectly" designed, the rate becomes a secondary concern. This has emboldened scholars to propose higher top-end rates as a means to address wealth inequality and corporate monopoly power.
- The 80% Proposal: Avi-Yonah’s recent work marks a watershed moment in this shift, explicitly linking the concept of deglobalization—where capital is less mobile due to shifting geopolitical landscapes—with the ability to tax domestic corporations at unprecedented levels without causing capital flight.
Supporting Data: Why the Standard Model Fails at the Extremes
The allure of the "rate-neutral" tax system relies on the assumption that under full expensing, the tax rate cancels out in the investment decision formula. Mathematically, if an investment is fully expensed ($z=1$), the required pre-tax return ($c$) becomes equal to the sum of the after-tax return ($r$) and depreciation ($delta$). In this idealized scenario, the tax rate ($tau$) disappears from the equation.
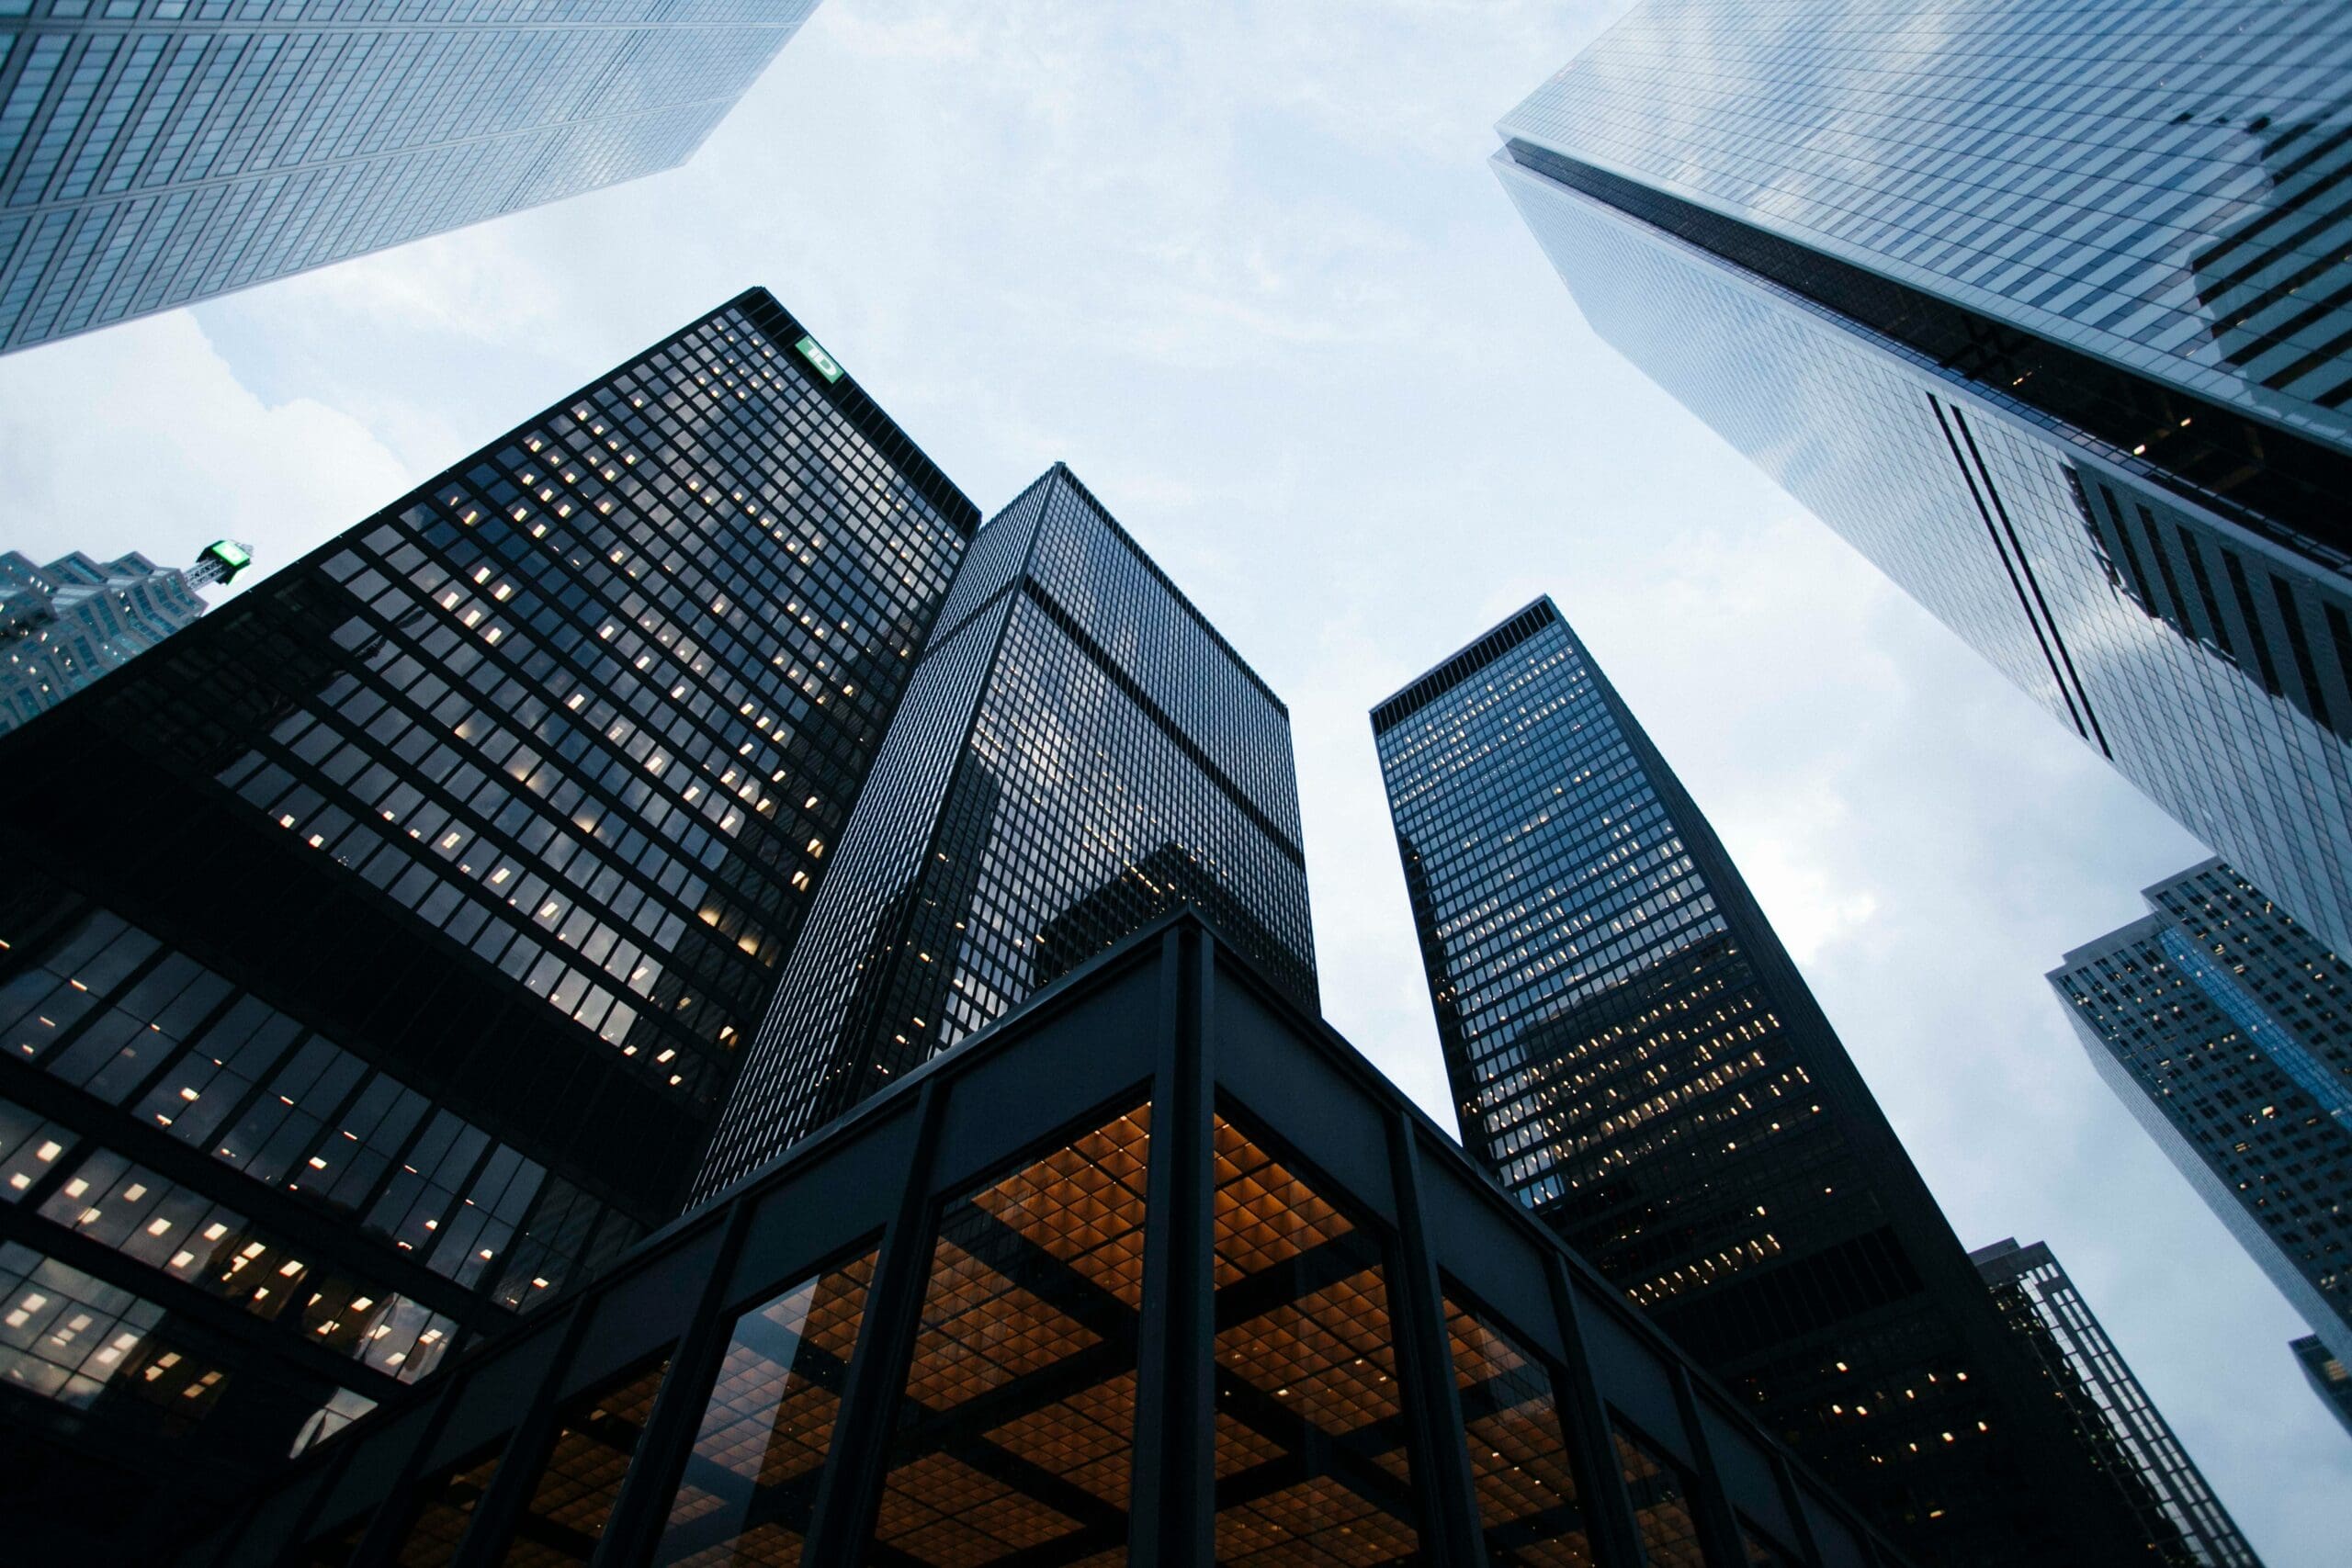
However, this model is a simplification that ignores the "sweat equity" and non-deductible inputs that define modern innovation.
The Entrepreneurial "Implicit Wage" Gap
Consider an entrepreneur building a startup. They often work for "implicit wages"—accepting a salary far below market value to ensure the company’s survival. This opportunity cost is never deductible for tax purposes. When an entrepreneur calculates whether to invest, they must factor in that the government will take 80 percent of the eventual profit, but will provide no relief for the years of unpaid labor the founder contributed to get there.
Quantitative Impacts
Using an extension of the user cost formula, researchers have modeled the impact of raising the corporate rate in an environment with implicit labor costs.
- The 21% to 31% Jump: Raising the rate by 10 percentage points from current levels increases the required pre-tax return by roughly 6 percent.
- The 70% to 80% Jump: Raising the rate by the same 10 percentage points from a 70 percent base increases the required return by 31 percent.
The data demonstrates a "convexity" of harm: as tax rates climb, the economic distortion grows exponentially rather than linearly. At an 80 percent rate, the penalty on innovation becomes prohibitive, regardless of how "clean" the underlying tax base is.
Official Perspectives and Counterarguments
Critics of the high-rate movement, such as Kyle Pomerleau of the American Enterprise Institute, argue that the "fix the base" strategy is a necessary but insufficient condition for high rates. They contend that the U.S. tax system is far too complex for a single-policy solution like full expensing to neutralize the damage of an 80 percent marginal tax rate.
"The danger," notes one analyst, "is that policymakers will use the academic admiration for expensing as a justification for punitive rates, ignoring the fact that full expensing doesn’t fix the underlying issue of capital misallocation at high rates."
Furthermore, proponents of a Destination-Based Cash Flow Tax (DBCFT) argue that while Avi-Yonah’s proposals—such as a 10 percent tariff and digital services taxes—aim to mirror the benefits of a DBCFT, they lack the structural integrity of a true border-adjusted system. A DBCFT, which denies import deductions while exempting exports, is designed to be neutral. Mixing these elements with a highly progressive, 80 percent rate creates a hybrid system that may satisfy ideological goals but fails the test of economic efficiency.
Implications for the Future of Globalized Business
The implication of Avi-Yonah’s thesis is that the world is entering an era of "deglobalization," where the mobility of capital is diminishing. If corporations are "trapped" by their need to access the massive U.S. consumer market, they may be forced to accept higher tax burdens.
However, this assumption is fraught with risk:
- Innovation Stagnation: If the cost of capital for startups rises significantly due to high tax rates on future success, the next generation of "unicorn" companies may never be founded.
- Compliance Costs: Moving toward a system that tries to capture "monopoly rents" requires the government to determine what constitutes "monopolistic or cartel-like behavior." This invites a level of administrative complexity and political cronyism that historically leads to lower, not higher, economic efficiency.
- The "Success Tax": A progressive rate structure based on profit thresholds (e.g., the $10 billion mark) creates a massive disincentive for growth. Firms will actively restructure or fragment their operations to stay below the threshold, leading to a "small-firm bias" that hurts the U.S. economy’s competitive edge.
Conclusion
While the intellectual rigor behind the "fix the base" movement provides a valuable blueprint for cleaning up the U.S. tax code, it serves as a dangerous foundation for the advocacy of extreme tax rates. Full expensing is indeed a pro-growth tool, but it is not a magic shield that protects the economy from the consequences of an 80 percent corporate tax rate.
As the debate continues, policymakers must distinguish between the efficiency of a tax base and the reality of tax rates. An efficient tax system is one that minimizes distortions, and no amount of structural reform can hide the fact that an 80 percent tax on corporate profit is a significant, and likely insurmountable, barrier to long-term economic dynamism. The "fix the base" approach should be viewed as a means to create a sustainable, competitive tax environment—not as an excuse to raise the stakes to a level that threatens the very innovation it seeks to capture.
