





In the evolving discourse of international fiscal policy, a compelling, albeit controversial, narrative has taken root: the idea that if a nation sufficiently "cleans up" its tax base—by eliminating loopholes, curbing profit shifting, and adopting full expensing—the traditional economic anxieties surrounding high corporate tax rates will effectively vanish. This argument has found a new, high-profile proponent in legal scholar Reuven Avi-Yonah. In a forthcoming article for the Tax Law Review titled “Taxation and Deglobalization,” Avi-Yonah posits that with the right structural reforms, the United States could safely implement a top marginal corporate income tax rate as high as 80 percent.
While the appeal of this "fix the base, raise the rate" strategy is clear, it rests on a theoretical foundation that, upon closer inspection, appears to be built on sand. While reforming the tax base is a worthy and necessary endeavor, the assumption that doing so renders the marginal tax rate economically neutral is a dangerous misunderstanding of how capital markets and entrepreneurship actually function.
The Evolution of the "Fix the Base" Argument
The argument for broadening the tax base—often championed by scholars like Kimberly Clausing, Jason Furman, Michael Linden, and Samantha Jacoby—is rooted in the desire for a more neutral, efficient tax system. The logic is that by eliminating special-interest deductions and curbing the ability of multinational corporations to shift profits to low-tax jurisdictions, governments can raise significant revenue without distorting economic behavior.
Historically, this movement has advocated for a "grand bargain": clean up the base, and in exchange, accept a moderate increase in the statutory rate. However, Avi-Yonah’s recent work marks a significant departure from this middle-ground approach. By suggesting that an 80 percent rate is viable, he has pushed the conversation to a radical extreme. His thesis is predicated on the belief that we are entering an era of "deglobalization," where the mobility of capital—the primary defense against high corporate taxation—is constrained. In this view, if firms cannot easily flee to tax havens without losing access to the lucrative U.S. market, they can be taxed at significantly higher rates without triggering the capital flight that characterized the era of hyper-globalization.
The Economic Mechanics of Full Expensing
To understand why experts like Avi-Yonah believe high rates might be sustainable, one must look at "full expensing." Under standard tax rules, businesses must depreciate assets over several years, which artificially inflates their taxable income and discourages investment. Full expensing allows firms to deduct the full cost of an investment immediately.
In the standard neoclassical economic framework—the Hall-Jorgenson model—the "user cost of capital" is the threshold return an investment must earn to be profitable. When full expensing is implemented, the tax rate mathematically drops out of the user cost formula. Theoretically, if the tax is levied only on "pure economic rents" (excess profits above the cost of capital) rather than on the investment itself, the tax becomes neutral.
This is where the theoretical model and the messy reality of the modern economy collide. The model assumes that every cost is deductible and every gain is taxable. In reality, the tax code is rife with asymmetries.
The Hidden Costs: Why the Rate Still Matters
The primary flaw in the "80 percent" proposal is the assumption that the tax rate ceases to matter once the base is "perfect." Even with full expensing, the tax rate remains a critical variable for three fundamental reasons:
1. The Problem of "Sweat Equity" and Implicit Wages
Entrepreneurs frequently work for years for little to no salary to build a company. This "sweat equity" represents a massive, non-deductible investment of time and labor. Because the tax code does not allow entrepreneurs to deduct their foregone market wages as a business expense, the investment in the business is not fully shielded from taxation.
When you raise the corporate tax rate to 80 percent, you are effectively imposing a massive tax on the entrepreneur’s personal effort. As the analysis of the user cost formula suggests, raising the business tax rate from 21 percent to 80 percent could increase the required pre-tax return on a project by over 114 percent. At such levels, even the most promising startups may find that the risk-adjusted return no longer justifies the effort.
2. The Asymmetry of Losses
The tax system is not a perfect mirror; it treats gains and losses differently. If a business loses money, it cannot always immediately monetize its tax deductions. For venture-backed startups, failure is the norm, not the exception—data shows that a significant majority of such firms are terminated at a loss. When a company is in a loss position, the tax benefits of "full expensing" are deferred or lost entirely. Thus, a high tax rate acts as a penalty on success while providing little to no offset for the risks of failure.
3. Intertemporal Distortions
Avi-Yonah’s proposal suggests a progressive rate structure, where smaller companies pay lower rates and companies with profits over $10 billion pay up to 80 percent. This creates a massive "tax cliff." A firm approaching the $10 billion profit threshold faces a staggering incentive to suppress growth or restructure simply to avoid the 80 percent bracket. Furthermore, if a firm incurs costs at a lower tax rate in its early years but realizes massive profits at an 80 percent rate later, the intertemporal mismatch creates a significant distortion that discourages long-term capital formation.
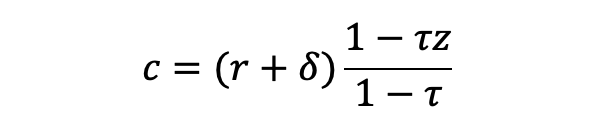
Official Responses and the Policy Debate
The proposal for an 80 percent rate has been met with skepticism from across the political spectrum. Critics, including tax policy experts like Kyle Pomerleau, argue that while the U.S. tax base certainly needs improvement, the "rate hike" solution is fundamentally unwise. The consensus among mainstream economists is that while base broadening can provide a temporary revenue boost or allow for a lower rate, it is not a "magic bullet" that permits the government to ignore the negative effects of high marginal taxation.
The debate is further complicated by the push for a Destination-Based Cash Flow Tax (DBCFT). Proponents argue that by shifting to a system that taxes consumption within the U.S. and denies deductions for imports, the government could effectively combat profit shifting. While Avi-Yonah’s proposals—such as a 10 percent tariff and a digital services tax—are clearly inspired by this direction, they lack the structural integrity of a true DBCFT. They are, in essence, protectionist measures masquerading as tax base reforms.
Implications for the Future of U.S. Competitiveness
If the U.S. were to adopt an 80 percent corporate tax rate, the implications for domestic investment and innovation would be profound.
- Capital Allocation: Investors would prioritize tax avoidance strategies over productive investment. Even if profit shifting is more difficult, the sheer incentive provided by an 80 percent rate would lead to massive investment in "tax engineering" rather than R&D or infrastructure.
- The "Innovation Premium": Startups are the primary engine of U.S. productivity growth. A tax regime that disproportionately penalizes the successful scale-up of these firms would likely lead to a decline in the formation of new businesses.
- Deglobalization Risks: While Avi-Yonah argues that deglobalization makes high taxes more feasible, the opposite may be true. In a world where the U.S. is one of many competing jurisdictions, an 80 percent tax rate would make the U.S. a pariah for global capital. Even if capital is "sticky," there is a point where the cost of doing business becomes prohibitive, leading to a slow but steady erosion of the tax base itself.
Conclusion: The Danger of Theoretical Purity
The desire for a robust tax base is a noble goal. Replacing inefficient, narrow-based taxes with broad-based, pro-growth alternatives like full expensing is a policy direction that would undoubtedly benefit the U.S. economy. However, the intellectual leap from "improving the base" to "taxing at 80 percent" is a bridge too far.
The economic reality is that the tax rate is never neutral. It acts as a wedge that distorts decision-making, influences the risk-taking behavior of entrepreneurs, and determines the ultimate allocation of capital. By ignoring the real-world friction of sweat equity, loss asymmetry, and the dynamic response of firms to punitive rates, proposals like those offered by Avi-Yonah risk trading long-term prosperity for short-term revenue gains.
Policymakers should continue to pursue the "fix the base" agenda, but they must do so with the clear-eyed understanding that the rate itself remains the most potent tool in the tax arsenal—one that, if misused, can do lasting damage to the very engine of growth it intends to fund.
