
By David Taube
Published September 18, 2026
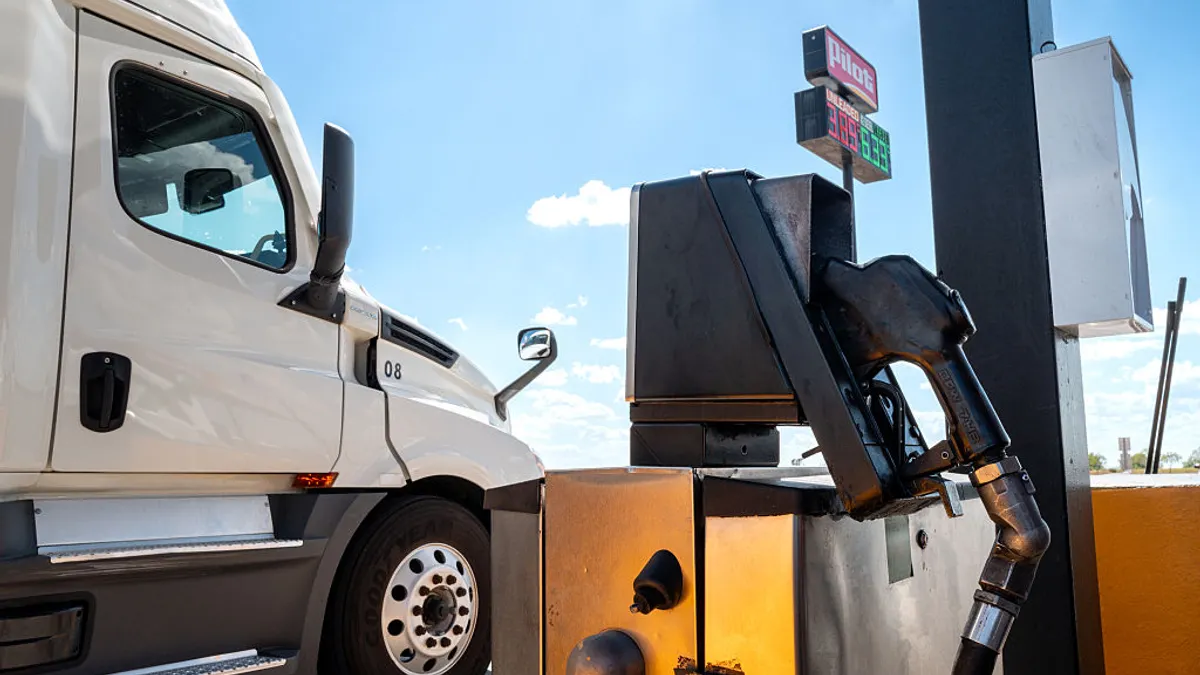
The American trucking industry is currently grappling with a fiscal shock of historic proportions. As of mid-September 2026, the national average for on-highway diesel has surged at an alarming rate, marking back-to-back weeks of record-setting price increases. For a sector already navigating the headwinds of soft consumer demand and mounting regulatory burdens, this sudden spike in energy costs is not merely a line-item inconvenience—it is a potential catalyst for a systemic industry contraction.
The Current Crisis: A Statistical Overview
The magnitude of the price hike observed in September 2026 has sent shockwaves through logistics boardrooms. According to data reported on September 14, the U.S. national average for diesel climbed nearly 32 cents in a single week. This sharp ascent followed an even more dramatic increase of nearly 37 cents just seven days prior.
This rapid escalation has effectively rewritten the cost-of-operation calculus for thousands of carriers, from independent owner-operators to large-scale national fleets. While diesel is traditionally viewed as a "pass-through cost" in the freight world—meaning the expense is theoretically borne by the shipper via fuel surcharges—the reality is far more nuanced and, for many, deeply problematic. The velocity of these price spikes is outpacing the adjustment mechanisms embedded in most standard freight contracts, leaving carriers to shoulder the immediate financial burden of every mile driven.
Chronology of the 2026 Diesel Surge
The instability of fuel prices throughout 2026 has been characterized by intermittent volatility, but the September surge represents an escalation in intensity.
- Early September 2026: Market analysts began noting a tightening of global supply chains and localized supply constraints, which started to manifest as upward pressure on pump prices.
- September 7, 2026: Reports confirmed a week-over-week increase of approximately 37 cents, marking the beginning of the current crisis.
- September 14, 2026: The U.S. on-highway diesel average recorded a secondary jump of 32 cents. The cumulative impact of these two weeks has placed the national average at levels that threaten the thin profit margins typical of the trucking sector.
- Mid-September 2026: Industry sentiment shifted from cautious observation to active alarm, with trade groups and individual operators expressing deep concerns regarding the sustainability of current freight rates in the face of such rapid overhead inflation.
The Anatomy of Fuel Surcharges: Why Theory Lags Behind Reality
Fuel surcharges (FSCs) are the primary tool used to shield carriers from the volatility of fuel markets. These surcharges are typically pegged to the Energy Information Administration’s (EIA) weekly retail diesel price report. As RJ Logistics has noted in industry analysis, the EIA’s methodology is designed for consistency: every Monday at 8:00 a.m., the agency surveys a representative sample of outlets across the contiguous United States. The data is then released every Tuesday.
While this system provides an objective benchmark that prevents disputes between shippers and carriers, it is fundamentally a "lagging indicator." In a market where fuel prices can spike overnight, waiting for the weekly EIA update means that carriers are often forced to operate for several days, or even a full week, using fuel purchased at prices significantly higher than the rate at which their surcharges are currently calculated.
For a carrier operating on tight margins, this "lag gap" can mean the difference between a profitable trip and a net loss. Even when contract rates are successfully renegotiated, the administrative burden and the delay in implementation create a "financial drag" that compounds over the course of a fiscal quarter.

Implications for Freight Networks: The "Deadhead" Dilemma
The impact of high diesel prices extends beyond the cost of the fuel itself; it fundamentally alters the strategic planning of freight routes. When fuel prices are low, carriers have more flexibility to accept loads that might involve less-than-ideal return paths. However, when fuel prices reach the current record-setting levels, the cost of "deadheading"—moving a truck empty—becomes prohibitive.
Carriers are now forced to be hyper-selective about the freight they haul. If a return trip does not offer a high enough rate to cover the astronomical cost of diesel, a carrier may refuse the load entirely, choosing instead to park the truck rather than operate at a loss. This defensive posture is already contributing to a tightening of available capacity, which, ironically, may lead to higher shipping costs for retailers and consumers in the long run.
Industry Sentiment and "Restlessness"
The psychological impact on the trucking workforce is palpable. Industry analysts and insiders like Croke have noted a distinct shift in the mood of the trucking community. The term "restless" is increasingly used to describe the attitude of carriers who feel they are being squeezed from both ends—rising operational costs and stagnant or declining freight demand.
"We’re starting to see carriers become very concerned and quite restless about where things are going," Croke observed in recent updates. This restlessness is not merely about fuel prices; it is about the broader uncertainty of the economic landscape. When fuel is high, the margin for error disappears. A single mechanical failure, a delayed load, or a traffic jam now carries a much higher financial penalty than it did even six months ago.

The "Perfect Storm": Regulatory and Demand Pressures
The diesel crisis does not exist in a vacuum. It is hitting the industry at a time when carriers are already struggling with several other systemic challenges:
- Sluggish Consumer Demand: Throughout 2026, freight tonnage has remained choppy. Retailers, wary of high inventory levels, have been cautious with their orders, leading to less consistent freight volumes across broad sectors.
- Regulatory Pressures: The industry is currently contending with significant federal oversight. Recent debates and legal challenges regarding the certification of non-domiciled CDL holders and stricter safety compliance for driving schools have added layers of administrative cost and operational friction.
- Market Contraction: The cumulative effect of these pressures is a "less-is-more" environment. There is less freight to move, and as the weakest carriers are forced to exit the market due to bankruptcy or consolidation, there are fewer trucks to move it. While this might eventually lead to a rebalancing of the market, the short-term impact is one of extreme instability.
Looking Ahead: Is Stability Possible?
As the industry looks toward the final quarter of 2026, the primary question remains: when will the volatility subside? Historical data suggests that fuel markets are cyclical, but the current geopolitical and economic environment makes long-term forecasting difficult.
For the trucking industry, the path forward requires a renewed focus on efficiency. Carriers are increasingly looking toward fuel-optimization software, alternative fueling strategies, and aggressive contract renegotiations to survive the current climate. However, these are secondary measures; the primary need is for a stabilization of fuel costs to allow for long-term capital investment.
The coming weeks will be critical. If fuel prices continue to climb, the industry may see a sharp acceleration in the rate of business closures, particularly among smaller, owner-operator-led firms that lack the liquidity to weather prolonged periods of extreme volatility. For the broader supply chain, this means that the risk of service disruptions remains high.
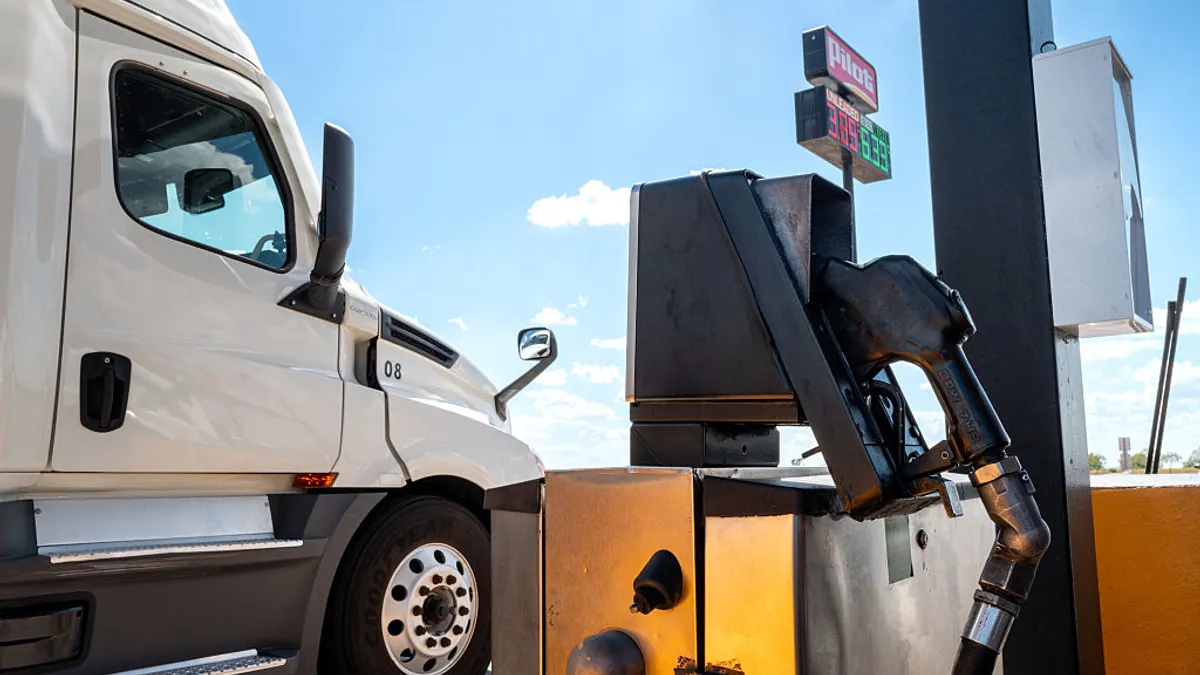
In summary, the record-setting diesel prices of September 2026 represent a major inflection point. The trucking industry has always been the backbone of the U.S. economy, but it is currently a backbone under extreme duress. How carriers, shippers, and regulators navigate the next few months will likely define the structure of the logistics landscape for years to come. The era of cheap, predictable fuel appears to be firmly in the rearview mirror, and the industry must now adapt to a new, more expensive reality.
