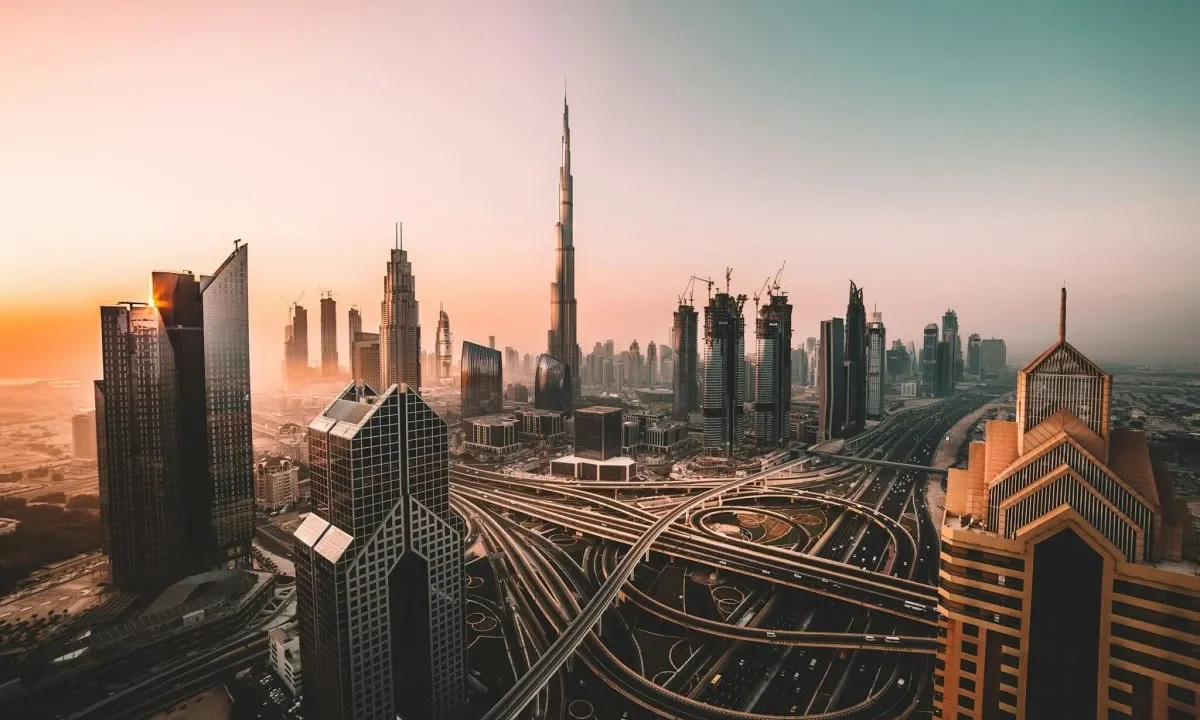

The United Arab Emirates (UAE), long considered the undisputed jewel of Middle Eastern tourism, is currently navigating a period of profound structural adjustment. Faced with the lingering economic tremors of regional instability—most notably the heightened tensions surrounding the U.S.-Iran geopolitical friction—the nation’s hospitality sector is undertaking a strategic pivot.
As sky-high aviation fuel costs and complex flight corridors render long-haul travel from Western markets increasingly prohibitive, major hotel operators are recalibrating their marketing engines. The objective is clear: double down on short-haul connectivity. By focusing on the massive, emerging travel cohorts from India, China, and Russia, the UAE is effectively redrawing its tourism map to ensure resilience in an era of persistent volatility.
The Strategic Shift: A Focus on Proximity
For decades, Dubai and Abu Dhabi operated under a "global reach" mandate, positioning themselves as the ultimate transit hubs for travelers flying between Europe, the Americas, and Asia. However, the current landscape of high airfares and fluctuating geopolitical risk has forced a reality check.
"We’re targeting short-haul markets like India, China, and Russia, that are a five- to six-hour flight away," explains Saurabh Tiwari, Vice President for the Middle East, Maldives, and Sri Lanka at IHCL (Indian Hotels Company Limited), which operates the prestigious Taj brand. "Since jet fuel prices are significantly higher than in previous cycles, it is difficult to expect travelers to justify the cost and effort of coming from markets like the Americas or Australia. Attracting visitors from those long-haul regions is, for the time being, largely wishful thinking."
This admission represents a significant departure from the post-pandemic "revenge travel" boom, which saw a surge of affluent tourists from across the globe. Today, the strategy is dictated by the economics of the flight path. When flight costs account for a larger share of the total vacation budget, the consumer’s propensity to choose a destination within a six-hour radius increases exponentially.
Chronology of a Crisis: Navigating Instability
To understand the current pivot, one must look at the timeline of the factors influencing the UAE tourism sector:
- 2020–2022 (The Recovery Phase): The UAE led the world in reopening its borders, benefiting from a pent-up demand surge. During this period, the luxury segment saw record-breaking occupancy rates as travelers sought "safe havens" amidst global lockdowns.
- Late 2023–Early 2024 (The Geopolitical Shift): The escalation of regional tensions—specifically the shadow conflict between the U.S. and Iran—began to manifest in the tourism sector. Insurance premiums for aviation surged, and airlines began rerouting flight paths, leading to longer flight times and higher fuel consumption.
- Mid-2024 (The Pricing Squeeze): As jet fuel prices stabilized at a higher plateau, the "long-haul premium" became a barrier to entry. Major carriers, faced with rising operational costs, passed these expenses to the consumer, effectively pricing out the average middle-class tourist from distant markets.
- Current Status (The Short-Haul Pivot): Industry leaders are now aggressively realigning their loyalty programs and marketing spends to capture the "middle-class boom" from India and the rebounding outbound volume from China and Russia.
Data-Driven Trends: Who is Filling the Hotels?
The data supports the necessity of this shift. India has emerged as a cornerstone of the UAE’s tourism recovery. Its geographical proximity, combined with the sheer volume of outbound travelers and the aggressive expansion of low-cost carriers (LCCs) like IndiGo and Air Arabia, has made it a reliable engine for hotel occupancy.
Market Performance Metrics (2024 Estimates)
- India: Currently accounts for approximately 15–20% of total international arrivals in Dubai, with a year-on-year growth rate exceeding 12% in the leisure segment.
- Russia: Despite international sanctions and logistical hurdles, Russian travelers remain among the top spenders in the luxury hospitality sector. The UAE’s status as a "neutral" hub has made it a primary destination for the Russian demographic.
- China: The return of the Chinese traveler, following the slow reopening of outbound tourism, is expected to provide the final piece of the puzzle for the UAE’s hotel occupancy recovery in Q4 2024 and beyond.
Furthermore, the "affordable luxury" narrative is gaining traction. As Tiwari noted, the softening of room rates in certain segments of the Dubai market is intentionally designed to capture the growing middle-class segments from these short-haul markets, who may have previously viewed Dubai as an unattainable, ultra-luxury destination.
Official Responses and Industry Outlook
The Department of Economy and Tourism (DET) in Dubai has remained characteristically optimistic, emphasizing that the UAE’s infrastructure is built for long-term sustainability. While the government acknowledges the challenges posed by regional instability, it continues to invest in "destination marketing" that highlights cultural immersion, family entertainment, and business connectivity.
Industry analysts at major hospitality groups note that the shift in source markets is not just a defensive measure, but a maturation of the market. "By diversifying away from a reliance on Europe and the Americas, the UAE is insulating itself against the economic recessions currently plaguing those regions," says one senior analyst at a global tourism consultancy. "When the West sneezes, the emerging markets of Asia are providing the medicine."
However, there are concerns. The reliance on short-haul markets means the UAE is highly sensitive to the economic health of India and China. Any slowdown in the growth trajectories of these two giants could have a disproportionate impact on UAE tourism revenues.
Implications: The Long-Term Transformation
The pivot to short-haul tourism has several far-reaching implications for the UAE’s economic landscape:
1. The "Middle-Class" Democratization of Dubai
Historically, Dubai marketed itself as a playground for the ultra-wealthy. The new reliance on short-haul markets is necessitating a change in the hospitality mix. We are seeing an increase in mid-scale and lifestyle-oriented hotel openings rather than just five-star super-luxury properties. This is a strategic move to accommodate the burgeoning middle-class traveler from South Asia.
2. Aviation Policy and Infrastructure
The UAE’s national carriers, Emirates and Etihad, are likely to continue their strategy of "hub-and-spoke" growth. Expect to see more secondary cities in India and Russia being connected to Dubai and Abu Dhabi via direct, point-to-point flights. This minimizes the need for long-haul layovers and lowers the final price for the passenger.
3. Geopolitical Hedging
By positioning itself as the bridge between the East and the West, the UAE is engaging in a delicate diplomatic dance. Its ability to maintain its status as a neutral territory—welcoming visitors from both the U.S. and Iran, and from Russia and the West—is its greatest asset. The tourism sector is effectively acting as a barometer for this neutrality. If the UAE can maintain this "open for all" policy, it will continue to attract high-net-worth individuals who require a stable, luxury-rich environment in a volatile world.
4. The Sustainability of Growth
The question remains: Can this growth continue indefinitely? As long as global aviation fuel prices remain tethered to regional conflict, the long-haul market will remain stagnant. This means the UAE must focus on "value-add" experiences. It is no longer enough to offer a hotel room; the UAE must offer a holistic experience—shopping, theme parks, and cultural events—that justifies the flight time, even for those within a five-hour radius.
Conclusion: A Resilient Future
The UAE’s hospitality sector is currently in the midst of an evolution. By acknowledging the realities of the modern, fuel-sensitive, and geopolitically complex travel landscape, operators like IHCL and others are ensuring that the lights stay on and the rooms stay full.
While the "long-haul dream" of a truly global tourist base may be currently on pause, the strategic shift toward the short-haul markets of India, China, and Russia is proving to be a masterclass in agility. The UAE is not just waiting for the storm to pass; it is building a new, more robust ship—one designed to sail through the currents of the 21st century’s most pressing challenges. As long as the nation maintains its commitment to connectivity and market diversification, the horizon for UAE tourism remains, despite the regional turbulence, remarkably bright.
