





By Editorial Staff
Published September 4, 2026
The American manufacturing sector is currently navigating a period of unprecedented volatility and structural transformation. As global trade dynamics shift and geopolitical friction intensifies, the long-standing model of offshoring—once the bedrock of cost-efficiency—is being systematically dismantled. According to a landmark 2026 report from the Reshoring Initiative, the U.S. industrial base is at a crossroads, with manufacturers caught between the allure of domestic security and the harsh realities of labor shortages and cost instability.
While 36% of manufacturers report they are actively in the process of reshoring, the landscape remains fractured. A significant 31% of Original Equipment Manufacturers (OEMs) have signaled they have no intention of shifting production back to the United States, citing the prohibitive costs of domestic infrastructure and the maturity of existing global supply chains.
The Main Facts: A Divided Industry
The data suggests that the "easy" era of globalization has ended. For decades, companies outsourced to minimize labor costs. Today, that calculus has been inverted by tariffs, supply chain fragility, and a heightened focus on risk mitigation.
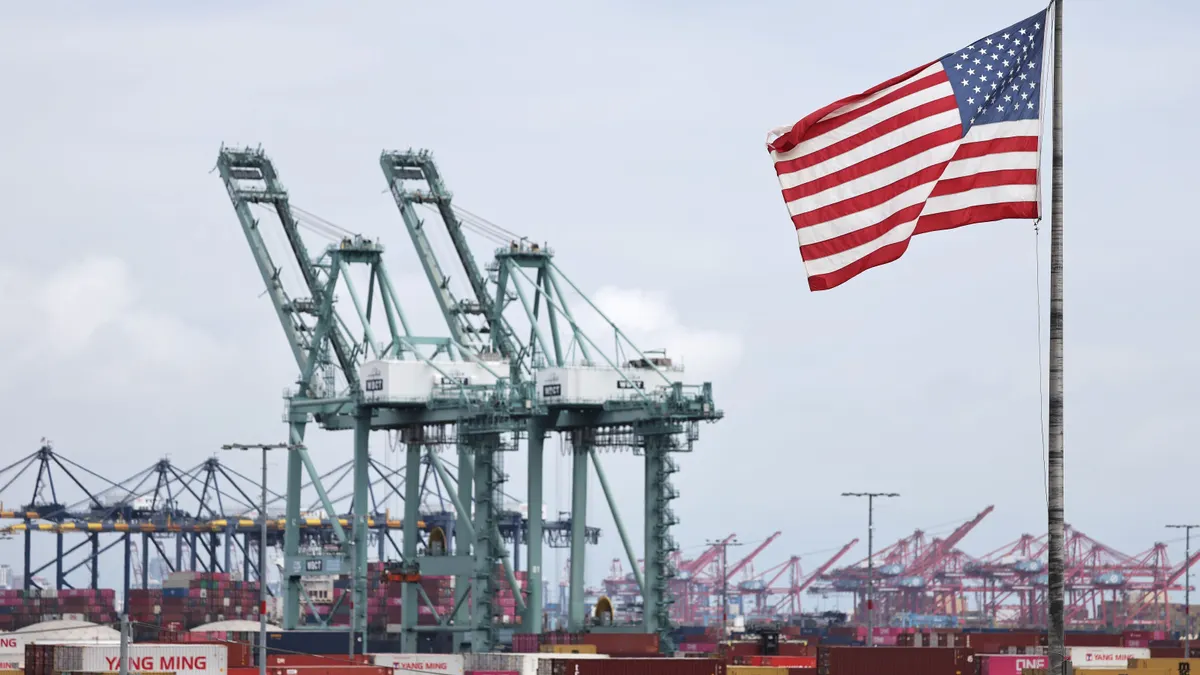
The Reshoring Initiative’s survey, which polled 118 OEMs and 131 contract manufacturers, reveals that the desire to reshore is being driven by two primary forces: tariffs and geopolitical instability. Approximately 65% of surveyed OEMs identified tariffs as their primary motivator for bringing operations home, while 60% pointed to the growing threat of geopolitical conflict as a major factor in their decision-making.
However, the decision to reshore is not a binary one. The industry is effectively split into three camps: those aggressively moving production, those standing pat to avoid the "moving target" of trade policy, and those who have no import footprint to begin with. This polarization indicates that while the policy environment is incentivizing domestic production, the operational hurdles—ranging from workforce gaps to raw material shortages—continue to act as a significant drag on widespread adoption.
A Chronology of the Reshoring Shift
To understand the current state of American manufacturing, one must look at the recent timeline of instability:
- 2024: The industry begins to grapple with the realization that global supply chains are fragile. Executives from the Institute for Supply Management (ISM) note a "wait-and-see" approach, with capital expenditures (CapEx) frozen due to fluctuating tariff regimes.
- 2025: The "Year of Hesitation." While many manufacturers express an intent to reshore, actual investment remains stagnant. Satisfaction rates among those who had already reshored remained high (96%), providing a temporary boost to the narrative of domestic growth.
- Early 2026: A sharp pivot occurs. The share of contract manufacturers quoting reshoring projects doubles from 16% to 32% year-over-year.
- September 2026: Tensions peak as the U.S. imposes fresh steel and aluminum tariffs on Canadian imports, triggering immediate retaliatory measures from Ottawa. This latest development underscores the primary complaint of modern manufacturers: the inability to forecast costs in an environment where trade policy can shift overnight.
Supporting Data: Moving Beyond Unit Cost
Perhaps the most significant shift in the 2026 data is the evolution of how manufacturers calculate value. For years, the "unit cost" of an item was the only metric that mattered. Today, that focus is shifting toward "Total Cost of Ownership" (TCO) and "Landed Cost."

In this year’s survey, 40% of manufacturers reported incorporating TCO into their procurement analysis, up from 30% in 2025. By looking at the full lifecycle of a component—including freight, inventory carrying costs, risk of disruption, and tariff exposure—many companies are finding that domestic production is becoming competitive for the first time in a generation.
However, the reality of the ground game remains difficult. The report notes that for every successful reshoring story, there is a counter-narrative regarding infrastructure. A recent study by the McKinsey Global Institute highlights a stark structural challenge: the current U.S. industrial base would need to double its capacity to meet the demands of a fully "reshored" economy. Simply put, we lack the domestic components and the manufacturing footprint to support a total return to American soil.
Official Responses and Industry Sentiment
The feedback from the manufacturing sector is characterized by a blend of optimism and frustration. For those who have successfully transitioned, the benefits are clear: improved speed-to-market, superior on-time delivery, and the elimination of the "freight tax" associated with long-haul international shipping.
However, the satisfaction rate has dropped significantly, from 96% in 2025 to 65% in 2026. This decline is not necessarily a failure of reshoring itself, but a reflection of the challenges involved in executing such a massive transition.

One OEM in the cold storage sector, which recently moved glass door procurement from Taiwan to Kentucky and Texas, provided a candid assessment of the struggle: "We have been impacted mostly by labor shortages." This is a recurring theme. The U.S. may have the capital to build factories, but it currently lacks the specialized labor force required to operate them at scale. The transition from a service-oriented economy to an industrial powerhouse requires a level of human capital investment that is currently lagging behind corporate investment in hardware.
Implications for the Future: The Need for Stability
The overarching takeaway from the 2026 report is that manufacturers are not necessarily ideological opponents of tariffs, but they are sworn enemies of uncertainty. The report explicitly states, "Manufacturers can plan around a known cost; they cannot plan around a moving target."
The ongoing trade friction with Canada is a prime example of the "moving target" problem. When an OEM signs a contract to move production from Asia to the Midwest, they are making a multi-year, multi-million dollar bet. If the cost of raw materials—specifically steel and aluminum—is suddenly impacted by an unexpected trade dispute, the financial model for that factory can collapse before the first production run is even completed.
The Path Forward
For the United States to successfully capitalize on the current desire for reshoring, policymakers and industry leaders must address three critical bottlenecks:
- Workforce Development: The chronic shortage of skilled labor is the single biggest barrier to domestic manufacturing. Without a robust pipeline of trade-trained workers, the factories of the future will remain empty.
- Regulatory Consistency: Trade policy must be viewed through the lens of long-term economic planning rather than short-term political maneuvering. Manufacturers need a predictable tax and tariff horizon to justify the massive capital expenditures required to repatriate supply chains.
- Infrastructure Scaling: As the McKinsey report highlighted, the U.S. industrial base is currently sized for a different economic era. Scaling up domestic production of intermediate components—the parts that go into the finished goods—is the missing link in the reshoring puzzle.
As we look toward the remainder of 2026 and into 2027, the trend toward reshoring appears irreversible, but its pace will be dictated by how quickly the U.S. can reconcile its industrial ambitions with its logistical and human resource realities. The "Great Pivot" is underway, but the road to a fully localized supply chain remains fraught with the complexities of a modern, interconnected, and increasingly volatile global economy.
