

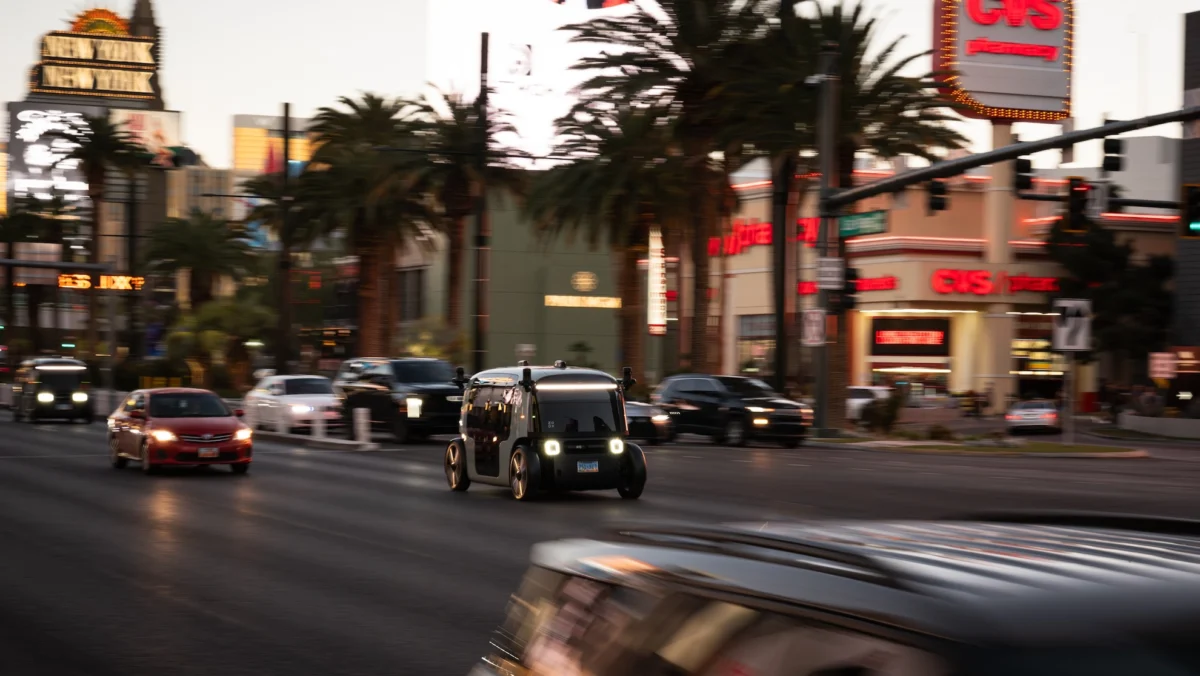
The global mobility landscape is undergoing a profound structural realignment. Driven by breakthroughs in artificial intelligence, evolving regulatory frameworks, and massive capital deployments, the transition from human-driven transport to autonomous, software-defined ecosystems is accelerating.
This transformation is highlighted by several landmark developments: Amazon-owned Zoox is preparing for its first commercial, paid robotaxi services; Uber has committed $10 billion to deploy a massive driverless fleet; and high-profile venture capital deals are reshaping logistics, manufacturing, and urban air mobility.
Main Facts: The Accelerating Commercialization of Driverless Fleets
Zoox’s Commercial Debut and Regulatory Precedent
On August 10, 2026, Zoox will officially begin charging passengers for rides in its custom-built robotaxis in Las Vegas, Nevada. While the company has previously operated pilot programs for employees and select passengers in Las Vegas and San Francisco—alongside early rider initiatives in Austin and Miami—this transition to paid rides marks its official entry into commercial operations.
The launch is made possible by a landmark exemption granted by the National Highway Traffic Safety Administration (NHTSA). Federal Motor Vehicle Safety Standards (FMVSS) historically mandated traditional driving controls, such as steering wheels, rearview mirrors, and pedals.
Because Zoox’s purpose-built vehicles are completely devoid of these manual controls, the company required a federal exemption to operate commercially. The newly issued NHTSA exemption permits Zoox to deploy a commercial fleet of up to 2,500 driverless vehicles for a period of two years.
Uber’s $10 Billion Autonomous Vehicle Commitment
Uber Technologies has solidified its position as the primary demand aggregator for the autonomous vehicle (AV) sector. Uber CEO Dara Khosrowshahi confirmed that the ride-hailing giant plans to invest $10 billion over the coming years to deploy approximately 120,000 third-party driverless vehicles across its global network.
Rather than developing proprietary autonomous hardware, Uber is executing a partner-centric strategy, positioning its platform as the operational and dispatch layer for developers like Waymo, BYD, and various emerging robotaxi operators.
Moove’s Capital Influx and Waymo Partnership
Moove, a mobility fintech startup founded in Africa and now headquartered in Dubai, has secured $250 million in Series C funding, pushing its valuation to $2.1 billion. Originally focused on vehicle financing for gig-economy drivers, Moove has expanded into a global fleet management powerhouse with over 42,000 vehicles across 13 countries.
The company has launched a dedicated autonomous vehicle division and currently serves as the primary fleet operator for Alphabet’s Waymo in Phoenix, Miami, and Las Vegas, with plans to expand to London. Notably, Moove plans to acquire Waymo’s specialized robotaxis directly and has already acquired the assets of another unnamed autonomous vehicle developer.
Chronology of Key Events (August 2026)
The rapid pace of industry developments during the first week of August 2026 underscores the momentum building across the mobility and advanced hardware sectors:
- August 1, 2026: Comprehensive analysis reveals the scale of Uber’s autonomous vehicle partnership empire, mapping alliances with major AV developers and forecasting its $10 billion deployment plan.
- August 4, 2026:
- Lucid Motors reports Q2 earnings, outlining a strict $1.4 billion cost-reduction initiative and delaying its affordable midsize Cosmos EV to late 2027.
- SpaceX delivers its first earnings report as a public company, showing a 100% year-over-year revenue increase fueled by Starlink expansion and enterprise AI compute deals with Anthropic and Google.
- Waymo eliminates its waitlist in Dallas, opening its driverless ride-hailing services to all residents and visitors.
- The New York Times publishes an investigative report detailing Uber’s legal defense strategy against more than 4,000 passenger sexual assault lawsuits.
- August 5, 2026:
- Zoox announces the August 10 commercial start date for paid robotaxi rides in Las Vegas.
- Moove announces its $250 million Series C funding round to scale its AV fleet management operations.
- Indian electric two-wheeler manufacturer River secures $120 million in Series C funding.
- Dutch bicycle conglomerate Accell Group is granted a suspension of payments, initiating formal insolvency proceedings.
- August 6, 2026:
- Tesla and SpaceX announce a joint $16.8 billion initial investment to construct "Terafab," an advanced semiconductor fabrication plant in Grimes County, Texas.
- Defense manufacturing startup Hadrian raises $1.37 billion at a $7.87 billion valuation.
- Ford Motor Company unveils the "Fathom," an affordable midsize electric pickup truck starting at $28,350, scheduled for a 2027 release.
Supporting Data: Funding Rounds, Earnings, and Market Metrics
The financial data from early August 2026 highlights a bifurcated market: massive capital concentration in defense, AI, and autonomous fleet infrastructure, contrasted with distress in legacy micro-mobility and capital-intensive EV startups.
Venture Capital and Private Equity Transactions
| Company | Sector / Technology | Transaction Details | Lead Investors |
|---|---|---|---|
| Hadrian | Advanced Defense Manufacturing | $1.37 Billion | WCM Investment Management, Washington Harbour Partners, Valor Equity Partners, 137 Ventures, Baillie Gifford |
| Moove | AV Fleet Management / Fintech | $250 Million (Series C; $2.1B Valuation) | Mubadala Investment Company, Woven Capital, Ion Pacific |
| River | Electric Two-Wheelers (India) | $120 Million (Series C) | Elev8 Venture Partners, Claypond Capital, Yamaha Motors, Al-Futtaim Group |
| Chargepoly | Heavy-Duty Fleet Electrification (France) | €23 Million ($26 Million) | Meridiam |
| AEM Group | Rare-Earth-Free Electric Motors (UK) | £16 Million ($21.5 Million) | Barclays Climate Ventures, PXN Ventures, Northstar Ventures, Low Carbon Innovation Fund |
| Matel Motion | Energy-Efficient Powertrains (India) | INR 130 Crore ($13.6 Million) (Series B) | UC Impower |
Corporate Distress: Accell Group’s Insolvency
In stark contrast to the high-valuation rounds in defense and autonomous technology, Dutch bicycle manufacturer Accell Group Holding (owner of Raleigh, Sparta, and Lapierre) filed for a suspension of payments. This filing initiates a formal restructuring and insolvency process.

The company was acquired just four years prior, in 2022, by a KKR-led consortium for €1.56 billion ($1.77 billion), reflecting the severe post-pandemic correction in the global micro-mobility and e-bike sectors.
Corporate Earnings and Capital Expenditures
SpaceX
In its inaugural earnings report as a publicly traded entity, SpaceX doubled its year-over-year revenue. Growth was driven by Starlink’s consumer and enterprise subscriber expansion, alongside high-margin business renting out proprietary high-performance computing power to AI developers Anthropic and Google.
Joby Aviation
The eVTOL pioneer reported narrowed net losses of $245 million for the quarter, bolstered by revenue generated via its acquisition of Blade Air Mobility. Joby also announced a strategic alliance with Atoms—the AI and industrial automation startup led by former Uber CEO Travis Kalanick—to develop and finance multimodal transportation hubs across Florida, Texas, New York, and California.
Lucid Motors
Under the direction of new CEO Silvio Napoli, Lucid reported a somber Q2. The luxury EV maker is executing a $1.4 billion cost-reduction plan and has delayed its critical midsize platform, the Cosmos EV, to the second half of 2027. The company’s long-term survival remains tied to future robotaxi integrations with Uber and Nuro.
Tesla & SpaceX "Terafab"
In one of the largest industrial real estate and technology investments of the decade, Tesla and SpaceX committed an initial $16.8 billion to break ground on "Terafab" in Grimes County, Texas. The facility will manufacture specialized semiconductors designed to run Tesla’s Full Self-Driving (FSD) software and SpaceX’s aerospace networks.
Official Responses, Regulatory Friction, and Litigation
The rapid commercialization of driverless technology has provoked significant regulatory and legal pushback from labor groups and public interest advocates.
The California DMV Class-Action Lawsuit
Teamsters California filed a lawsuit against the California Department of Motor Vehicles (DMV), alleging the state regulatory agency failed to conduct sufficient economic impact and safety studies before authorizing self-driving heavy-duty trucks on public highways.
The Autonomous Vehicle Industry Association (AVIA) issued a sharp rebuttal, stating:
"This lawsuit from the Teamsters sets a new standard in abusive and frivolous litigation and cannot be taken seriously."
AV developers named in the broader policy debate declined to comment on the pending litigation.
NHTSA’s Regulatory Safeguards on Zoox
The NHTSA’s two-year, 2,500-vehicle commercial exemption for Zoox represents a major shift in federal vehicle standards. However, it comes with strict oversight.
Zoox is required to submit continuous operational telemetry, safety reports, and immediate crash notifications to federal regulators. This temporary exemption serves as a regulatory test case for steering-wheel-free vehicles.

Uber’s Passenger Safety Litigation
While Uber advances its autonomous technology partnerships, it faces severe legal pressure regarding its legacy human-driven platform. A New York Times investigation detailed Uber’s aggressive defense strategies against more than 4,000 active lawsuits filed by passengers alleging sexual assault and violence by drivers.
The litigation highlights the significant liability risks associated with human-driven gig networks, providing a powerful financial incentive for Uber to transition to driverless operations.
Strategic Implications: The Future of Autonomous Ecosystems
[Traditional Auto OEM] ──> Needs Steering Wheel/Pedals (FMVSS Regulations)
                                  │
[Zoox NHTSA Exemption] ──> Bypasses Manual Controls (No Steering Wheel/Pedals)
                                  │
                                  ▼
[Tesla Cybercab / Future AVs] ──> Leverages Zoox Precedent to Accelerate Approvals
1. The Death of the Steering Wheel as a Regulatory Requirement
The NHTSA exemption granted to Zoox establishes a powerful precedent for the entire autonomous vehicle industry. Historically, developers designed AVs around modified production vehicles (such as Waymo’s integration of the Jaguar I-Pace) to comply with FMVSS rules requiring physical mirrors, steering wheels, and pedals.
With Zoox breaking this barrier, competitors like Tesla—which is currently developing its dedicated, two-seat "Cybercab"—can leverage this regulatory path to bypass manual driving controls entirely. This shift significantly reduces manufacturing complexity, lowers vehicle weight, and maximizes interior cabin space for passenger comfort.
2. The Rise of the AV "Asset Owner" and Fleet Operator Class
As AV technology matures, the business model is shifting from technology development to operational scale. Tech companies like Waymo and Zoox excel at software and sensor integration, but they lack the localized logistics infrastructure required to clean, charge, maintain, and deploy thousands of vehicles daily.
Moove’s $250 million funding round and its partnerships with Waymo indicate the rise of a new corporate class: the institutional AV fleet operator. These specialized entities will manage the heavy physical assets of the autonomous revolution, acting as the critical bridge between AV developers and ride-hailing demand platforms like Uber.
3. Open-Source AI vs. Proprietary AV Stacks
Nvidia’s commercial release of its Alpamayo 2 Super autonomous driving AI model on Hugging Face marks a shift toward open-source AV development. By offering an open-licensed, commercially redistributable model, Nvidia is democratizing autonomous software.
This allows smaller automakers, transit agencies, and logistics providers to bypass billions of dollars in proprietary R&D. Consequently, the competitive advantage in the AV sector is shifting away from software algorithms and toward physical manufacturing scale, compute access, and real-world testing miles.
4. Travis Kalanick’s Structural Return to Mobility
A decade after his departure from Uber, Travis Kalanick is quietly building a vertically integrated infrastructure empire to support the autonomous era. His startup, Atoms, is focusing on industrial automation and AI, while simultaneously partnering with Joby Aviation to develop and finance multimodal transportation hubs.
By hiring his former Uber Chief Financial Officer, Gautam Gupta, Kalanick is assembling a seasoned leadership team. As autonomous ground fleets and aerial eVTOLs scale, Atoms is positioning itself to control the physical hubs, charging stations, and maintenance depots that these vehicles will require to operate.
